

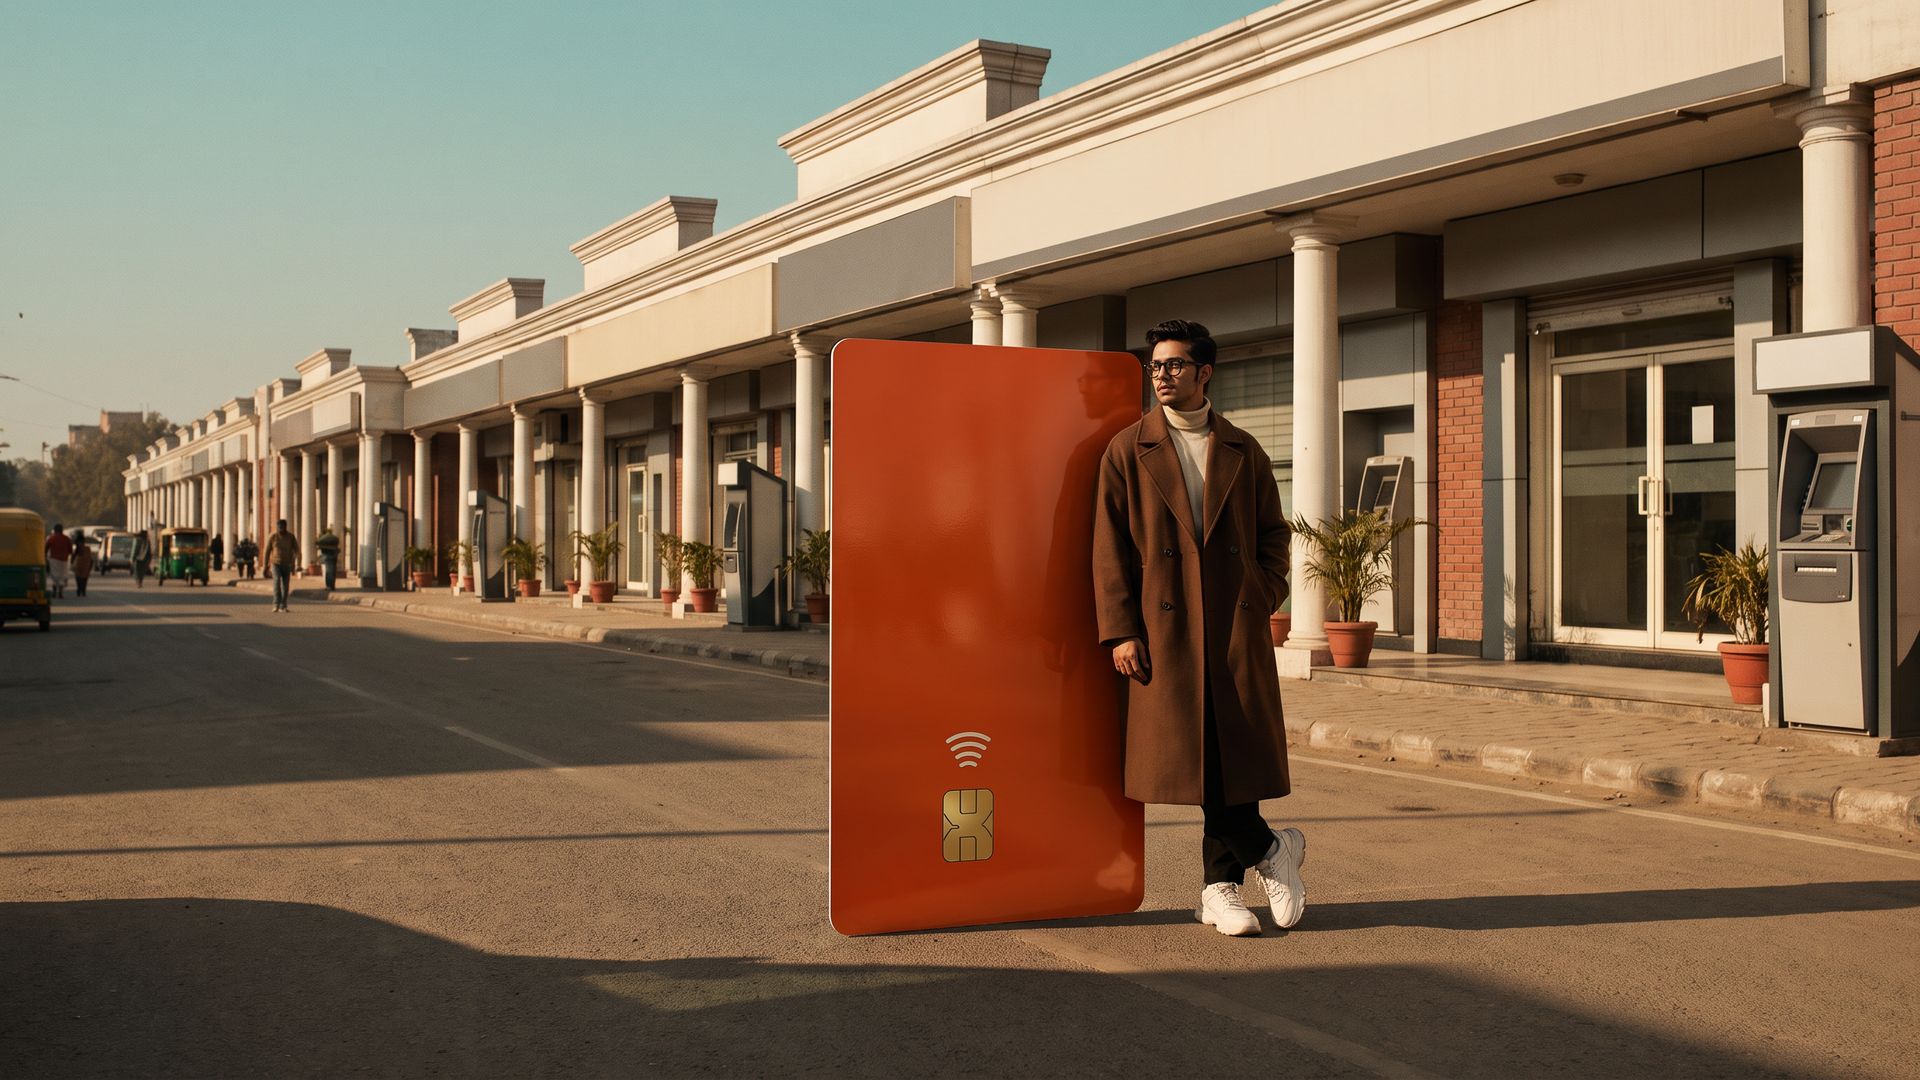
Stand on a busy Gurugram road with two bank branches a few doors apart. The fixed deposit boards show rates that are close. Both banks ask for the same KYC documents at the counter. Both are covered by the same deposit insurance scheme. A customer walking past has almost nothing on the product side to separate them, and that is exactly why the name over the door, the feel of the app and the voice on the phone decide where the salary account goes.
- Why does product parity make a bank’s brand more important, not less?
- Which regulator-driven design decisions does a bank brand have to make?
- What should a bank decide before it briefs a branding agency?
- Why branding matters for banks: two branches, one road
- Common mistakes when bank products are regulated and similar
- A checklist for designing regulated elements into a bank brand
- How to brief product and service teams, not only the agency
- People also ask
Why does product parity make a bank’s brand more important, not less?
When savings accounts, KYC steps and deposit insurance work the same way everywhere, the product stops being the reason to choose. The customer falls back on three quieter questions. Do I trust this bank with my money? Have I heard of it and do people like me use it? Will the app work when I need it at eleven at night?
Each of those is a brand question. Trust is built by consistency: the same name, the same tone and the same care across branch, app, SMS and call centre. Recognition is built by a clear identity used with discipline. Ease is a brand promise that the product team has to keep. A bank that gets these right earns room it would otherwise have to buy with a better rate or a bigger ad budget.
Parity also raises the cost of a weak first impression. People rarely move a salary account or a home loan for small reasons, so the bank that wins the first choice tends to keep the customer. This page expands one answer from our 100 bank branding questions.
| Touchpoint | What the rules fix | What the brand still decides |
|---|---|---|
| Name | The Banking Regulation Act reserves the words bank, banker and banking for banking companies | How the masterbrand, product names and subsidiaries sit together |
| Website and net banking | DICGC asks insured banks to show its logo and a QR code linked to its website, prominently | Where that mark sits in the layout and what trust signals stand beside it |
| Retail and MSME term loans | RBI requires a Key Facts Statement, including the annual percentage rate, before the loan contract is signed | Screen order, type, tone and how clearly the numbers read |
| Core product features | Broadly similar across banks | Naming, story, service design and the moments customers remember |
Which regulator-driven design decisions does a bank brand have to make?
Many agencies call themselves compliance-aware. The useful test is whether an agency can show the actual decision. Here are three we make on almost every bank brief.
- Where the deposit insurance mark sits. In July 2023 DICGC advised every insured bank to display its logo and a QR code linked to the DICGC website prominently on the bank’s website and internet banking portal, with effect from 1 September 2023. The decision is where “prominently” lands in your grid. We put it in one designed trust band on the home page and the login screen, beside the bank’s own security and grievance links, so every product page inherits it instead of each team placing it differently. If your small finance bank is registered with DICGC, the same rule applies to you.
- Where the Key Facts Statement falls in the loan journey. RBI requires lenders to give borrowers a Key Facts Statement before the loan contract is executed, for retail and MSME term loans sanctioned from 1 October 2024, and it includes the annual percentage rate. It must be in a language the borrower understands. In a digital journey that means the KFS screen sits before e-sign, reads as a branded screen rather than a buried PDF link, and makes the APR the most visible number on it. It also means the brand’s typefaces need Indic script support from day one, not as a later patch.
- How names and lockups carry the word bank. The Banking Regulation Act keeps the words bank, banker and banking for banking companies, with an exception for certain bank subsidiaries whose names show whose subsidiary they are. That shapes the lockup rule for a bank group: the securities, insurance or fintech arm cannot borrow the word freely, so the parent link has to be visible in the name and the mark. Our bank brand architecture playbook covers when to use a masterbrand or an endorsed model.
None of these is a design problem in the abstract. Each is a layout, sequence or naming problem with a rule attached, and each is cheaper to solve before the visual pass than after it.
When the rules make every bank’s product look the same, the brand is what the customer is choosing.
What should a bank decide before it briefs a branding agency?
Start with a parity check. List the products where you match competitors and the few where you lead. The brand has to carry the difference on the first list and prove it on the second.
SIGNALNewsletter by Yamm Labs
The next piece, straight to your inbox.
New writing on BFSI brands, B2B and influencer marketing, and AI search.
One click to unsubscribe. Privacy policy

Next, list the fixed elements: the deposit insurance mark, the loan KFS, grievance and security notices, and any product disclaimers. Hand them to the agency as part of the brief so they shape the layout from the start.
Then settle architecture. A bank with cards, loans, a securities arm and a digital app needs a rule for how those names relate before anyone draws a logo. Finally, set a budget band that covers the digital journeys, not only the identity. What that costs in rupees is covered in our fintech branding cost guide.
Our BFSI clients have included Axis Bank, HDFC Life, TATA AIA Life Insurance, Paytm Money and Aditya Birla Sun Life Mutual Fund. We work from Gurugram and serve banks and financial brands in India, the Gulf and elsewhere remotely.
Why branding matters for banks: two branches, one road
Go back to the two branches a few doors apart on the Gurugram road. Call them Bank A and Bank B. Their fixed deposit rates are close, the KYC documents are the same and both carry the same deposit insurance. On paper the customer has no reason to prefer one. In practice, the table above shows four places where one of them can pull ahead.
The name. Both are banking companies, so both can use the word bank. Bank A has a securities arm and a card app with names that look unrelated to the parent. Bank B shows the parent link in every name and lockup. A customer who trusts Bank B’s branch carries that trust into its app without having to work it out.
The website. Both display the DICGC logo and QR code, as they must. Bank A places it wherever each product team found space. Bank B puts it in one designed trust band beside its security and grievance links, on the home page and the login screen. Same rule, different impression.
The loan journey. Both give a Key Facts Statement before the contract. Bank A links to a PDF just before e-sign. Bank B shows the KFS as a screen in its own type, in the borrower’s language, with the APR as the clearest number on it.
The features. Here the rules leave the most room, and Bank B uses it: a clear name for each product, a service promise its app actually keeps, and an SMS tone that sounds like the branch. None of this changes the rate. All of it changes where the salary account goes.
Common mistakes when bank products are regulated and similar
Parity tempts banks into a few predictable errors. Each one wastes the room regulation leaves open.
- Competing only on rate. A rate advantage is easy to match and hard to remember. It rarely builds the trust that keeps a customer once a competitor matches it.
- Treating mandatory elements as fine print. The deposit insurance mark and the KFS are seen at moments of decision. Designed well, they read as care. Added late, they read as small print.
- Letting each product team brand itself. Cards, loans and the app drift into separate styles, and the customer stops seeing one bank behind them.
- Promising what the product cannot keep. A campaign about ease that leads to a slow app teaches customers to distrust the next campaign.
- Ignoring language. The KFS must be in a language the borrower understands. A type system without Indic script support breaks exactly there.
- Briefing the identity without the journeys. A new logo on unchanged screens changes little that customers feel.
A checklist for designing regulated elements into a bank brand
Use this list when a bank’s brand system is being built or refreshed. It covers the fixed elements this page has discussed and the places they appear.
- List every mandatory element: the deposit insurance mark, the loan KFS, grievance and security notices, and product disclaimers.
- For each one, note where it must appear and at which step of the journey.
- Design a single trust band for the website and internet banking that holds the DICGC mark with the bank’s own security and grievance links.
- Place the KFS screen before e-sign in every digital loan journey, with the APR as the most visible number.
- Check that brand typefaces cover the Indic scripts the bank will use for borrowers.
- Write a naming and lockup rule for subsidiaries so the parent link is visible where the law requires it.
- Give mandatory text a fixed slot in every template, rather than squeezing it in at the end.
Rules and circulars are revised. Confirm the current text of each requirement with your compliance team before the system is frozen and again before launch.
How to brief product and service teams, not only the agency
Ease is a brand promise that the product team has to keep. That means the brief cannot stop at the branding agency. The people who run the app, the branches and the call centre need the same one-page brief, in plain words.
Give them the promise in one sentence, and name the moments where it will be tested: opening an account, applying for a loan, reporting a lost card, raising a complaint. Ask each team what currently breaks the promise in their area. Their answers usually show where branding matters for banks more than any campaign does.
Then share the fixed elements and the layout rules for them, so product teams stop placing the deposit insurance mark and the KFS in their own way. Agree who owns each rule after launch. A brand system without an owner in each team drifts back to parity within a few releases.
Finally, set a regular review where the brand, product and compliance leads look at the same screens together. It is cheaper to catch a drifting tone or a buried disclosure in a monthly review than in a customer complaint.
People also ask
Is a bank’s brand just its logo and colours?
No. The logo is the most visible part, but customers judge a bank by the whole experience: the app, the branch, the SMS alerts and how a complaint is handled. A brand system sets the rules that keep all of those consistent.
How can a bank stand out when its products match competitors’?
By competing on the things regulation leaves open: service design, clarity, tone, speed and the moments customers remember. A clear promise that the product team actually keeps is harder to copy than a rate.
Do rules like the Key Facts Statement limit a bank’s brand creativity?
They fix what must be shown and when, and the KFS follows a standard format, but the bank still sets the type, tone and clarity of the screen. A well-designed KFS screen in the bank’s own type and tone builds trust at the exact moment a borrower is deciding.
Why does branding matter for banks in India specifically?
Indian banks share the same KYC steps, the same deposit insurance scheme and increasingly similar digital products, and rules such as the KFS fix parts of what they must show. That leaves trust, recognition and ease as the main reasons to choose one bank over another. Branding matters for banks here because it is the part of the offer regulation leaves open.
What does the DICGC mark do for a bank’s brand?
It tells a customer that the bank is insured under the deposit insurance scheme. Every insured bank must display it on its website and internet banking portal, so it does not set one bank apart from another. What does set a bank apart is how the mark is placed: inside a designed trust band next to security and grievance links, or scattered wherever space allowed.
Where should a bank with a small budget start on its brand?
Start with the fixed elements and the busiest journeys. Designing the trust band, the KFS screen and the account opening flow in one consistent style reaches every customer, costs less than a campaign and removes the most common signs of carelessness. Identity work can follow once those high-traffic screens feel like one bank.
Can a bank’s brand make up for a weak product?
Not for long. A brand can win the first choice, but a promise the product does not keep teaches customers to distrust the next one. When products are regulated and similar, the brand’s job is to make the bank’s real strengths easy to see and its fixed elements easy to trust, not to cover gaps.
Who inside a bank should own the brand?
Marketing usually leads, but the brand is kept or broken by product, operations, service and compliance. A practical model is one brand owner who holds the promise and the system, with a named person in each of those teams responsible for applying it. Without owners outside marketing, the app and the branch drift back to looking like every other bank.
Sources
Want to see where parity is costing your bank brand trust?
Get a free Fintech Brand Audit across 8 dimensions, plus 3 fixes. No pitch. Run the free Brand Audit →